
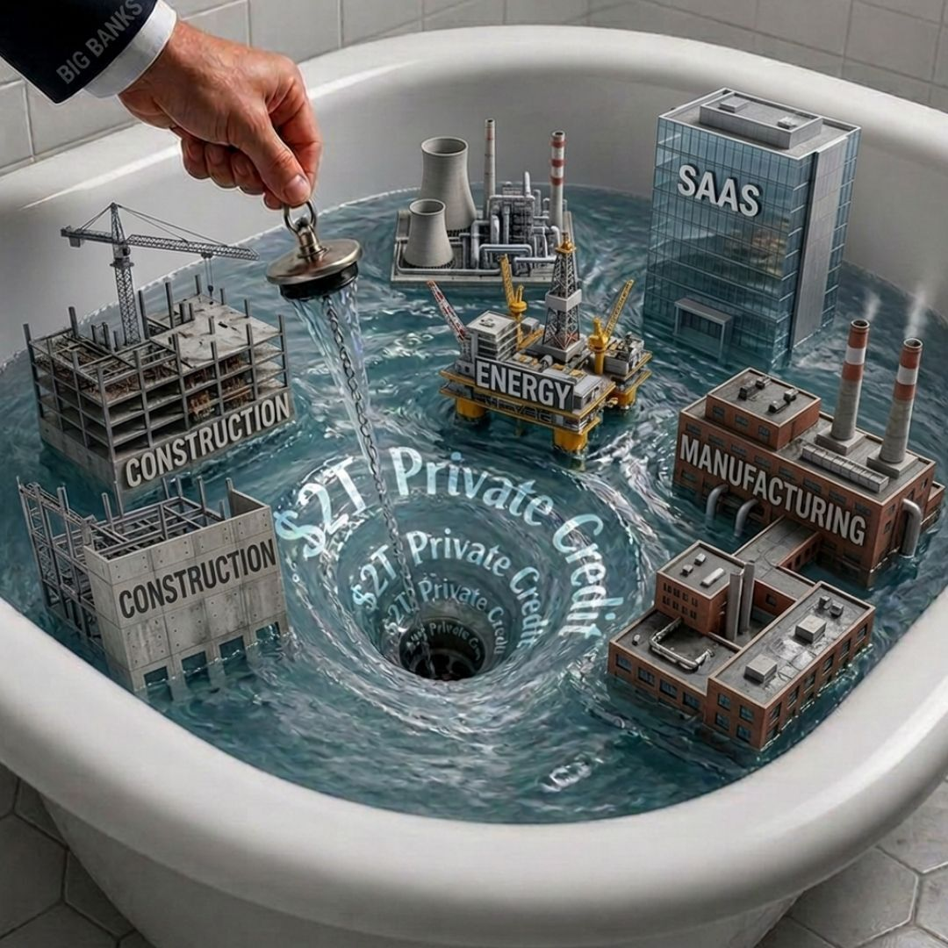
HSBC just told its private credit clients something they didn't want to hear: we're not renewing your lending facilities. The British banking giant is pulling back from a sector it once courted aggressively, citing concerns about risk and the need for "robust central oversight."
HSBC isn't alone. Barclays is constraining lending to structured finance counterparties with "vulnerable business models." J.P. Morgan marked down collateral held by private credit firms and slashed their borrowing capacity. Deutsche Bank, sitting on a €25.9 billion private credit loan portfolio, faces potential losses that Bloomberg Intelligence estimates could eat up 13% of its 2026 profit in a downturn scenario.
The retreat is on. And it's happening in a market estimated at $1.5 trillion to $2 trillion as of the end of 2024.
Spectacular Failures
What's driving major banks to abandon a sector they've spent years building? Two words: spectacular failures.
The alleged fraud at Mortgage Financial Solutions (MFS) sent shockwaves through the industry. HSBC took a $400 million charge from its exposure to Apollo's asset-backed lending unit Atlas SP, which had lent to MFS. Barclays CEO CS Venkatakrishnan pointed to MFS—along with the earlier collapse of US sub-prime auto lender Tricolor—as proof that strong financial controls at borrowers aren't optional luxuries.
"The importance of strong financial controls at borrowers" is banker-speak for "we got burned, and we're not getting burned again."
Barclays is now constraining lending to counterparties that "cannot demonstrate the quality and independence of their financial controls." Translation: if you can't prove your books are clean, you're not getting our money.
The problem is that private credit exists precisely because traditional lending standards are too restrictive for many borrowers. Companies turn to private credit funds when banks won't lend to them directly. Now those same banks are pulling back from financing the funds that finance the companies banks won't touch.
It's a circular firing squad, and businesses caught in the middle are about to feel the squeeze.
The Four-Institution Concentration Problem
Here's what should worry anyone paying attention: four institutions—Deutsche Bank, Barclays, BNP Paribas and HSBC—account for almost two-thirds of the €137 billion private credit exposure across surveyed geographies.
When the market is that concentrated, and those four players are simultaneously pulling back, you don't have a market correction. You have a liquidity crisis waiting to happen.
Deutsche Bank insists it's not exposed to "significant risks" from non-bank financial institutions, while acknowledging that "indirect credit risks could arise." That's the kind of carefully parsed language that should make anyone nervous. Indirect credit risks have a nasty habit of becoming very direct, very quickly.
J.P. Morgan's exposure to private credit totals roughly $22.2 billion. When the bank marked down collateral in March, it largely affected software companies—businesses whose vulnerability has been enhanced by the rise of artificial intelligence. If AI is making your business model obsolete, your collateral value is heading south, and your access to credit is evaporating.
Lovely Narratives vs. Hard Realities
In their April 2025 shareholder letter, J.P. Morgan executives Troy Rohrbaugh and Doug Petno struck an optimistic tone about private credit's future: "Despite increased scrutiny of private credit in recent months, we believe private markets will remain an important part of the financial system over the long term."
They noted that private companies far outnumber public ones, with many choosing to remain private longer due to "the high costs and complexities of public listings." Meanwhile, "surging investor appetite for private assets is reshaping capital flows and creating new opportunities for growth."
That's a lovely narrative. But it sits uncomfortably alongside the fact that J.P. Morgan just marked down collateral and reduced borrowing capacity for private credit firms.
If private credit is such a great long-term opportunity, why are you cutting exposure now?
The UK's Financial Stability Board described private credit as "essential for supporting economic activity, particularly in underserved sectors." But the same report noted that further work is needed to assess vulnerabilities in interlinkages between non-banks, liquidity mismatches, and supervisory capabilities.
"Further work is needed" is regulatory speak for "we don't fully understand what's happening here, and that makes us nervous."
What Happens Next?
Private credit emerged to fill a gap left by banks retreating from certain types of lending after the financial crisis. Now banks are retreating from private credit itself. So who fills this gap?
The FSB is right that private credit serves "underserved sectors." But those sectors are underserved for a reason—they're riskier. For example, it's estimated that software companies make up 20% or more of the loans in many private credit funds. When banks provided warehouse financing and revolving loan facilities to private credit funds, they were essentially providing a backstop. Remove that backstop, and the whole structure becomes more precarious.
Companies that "choose to remain private longer" may find their choices narrowing considerably. The high costs and complexities of public listings start looking more manageable when your alternative is no financing at all.
And what about the private credit funds themselves? They've been operating with the assumption that bank financing would be available when needed. That assumption is now being tested. Funds that can't demonstrate pristine financial controls and bulletproof business models are going to find their options limited.
The irony is rich: private credit funds exist because they're willing to take risks banks won't take. Now banks won't finance the funds because they're too risky.
Software, AI and Rewritten Economics
For the better part of a decade, private equity firms treated software businesses as the perfect acquisition target. The pitch was straightforward: subscription-based revenue streams delivered consistency, profit margins ran higher than traditional industries, and growth trajectories could be modeled with unusual precision. These characteristics made software companies particularly well-suited for the leverage that defines PE transactions.
Private credit lenders embraced the same logic. They underwrote billions in financing for these deals, betting that the same attributes that attracted PE buyers—revenue predictability, margin strength, scalable growth—would protect their positions even as debt loads climbed.
The investment thesis rested on a stable foundation: software economics were understood, defensible, and repeatable.
Then the ground shifted.
Artificial intelligence arrived not as an incremental improvement but as a fundamental challenge to the assumptions underpinning years of dealmaking. The technology doesn't simply compete with existing software—it threatens to rewrite the economics that made these companies attractive in the first place.
The question facing both PE firms and their private credit partners is whether the characteristics that justified aggressive leverage and premium valuations still hold in an environment where AI can potentially replicate functionality, compress margins, and accelerate commoditization.
The recurring revenue that looked so dependable may prove more fragile than the models suggested. The growth that appeared so predictable may face disruption that spreadsheets never contemplated. And the debt that seemed so manageable may be sitting on assets whose competitive position is suddenly uncertain.
What happens when the investment thesis meets a technology that undermines its core assumptions? We're about to find out.
A $2 Trillion Shadow Banking Sector
This isn't just about private credit. It's about what happens when a $2 trillion shadow banking sector that's "essential for supporting economic activity" suddenly loses the support of the traditional banking system.
Deutsche Bank's €25.9 billion exposure is up from €24.5 billion in 2024. That's growth in a sector the bank is supposedly concerned about. Either Deutsche Bank is terrible at risk management, or the economics of private credit lending were too attractive to resist—until they weren't.
HSBC says it will "focus on supporting deals globally for our most important clients, in regions where we see the most potential for growth." That's corporate communications language for "we're picking winners and abandoning everyone else."
The companies and funds that aren't among HSBC's "most important clients" are about to discover what it means to be unimportant.
When major banks retreat simultaneously from a multi-trillion-dollar market, they don't do it because everything is fine. They do it because they see something coming that they don't want to be exposed to when it arrives.
The question isn't whether private credit will survive this retreat. It will. The question is what it will look like on the other side—and how many businesses will be left standing when the dust settles.